The Reserve Bank has pushed interest rates higher for the fifth time this year as it tries to bring inflation back toward the target range of 2 to 3 per cent.
A recent Reserve Bank survey found inflation is the public’s top economic worry, but only about one quarter of respondents believe raising interest rates will reduce inflation, while almost 60 per cent think higher rates will make inflation worse.
The RBA’s single direct tool is the overnight cash rate, also called the official interest rate. That rate sets the baseline for the prices banks charge each other and, through added margins, for the loans and deposits offered to households and businesses.
When the RBA lifts the official rate, banks typically pass the increase through to variable-rate mortgages almost immediately, while fixed-rate loans with long terms take longer to adjust. Higher official rates also push up the interest paid to depositors, meaning savers can see improved returns.
The central bank describes four broad channels through which rate rises reduce inflation: higher borrowing costs for households and firms, stronger incentives to save, lower asset prices such as shares and housing, and a firmer exchange rate that makes imports cheaper.
Put plainly by economists, these effects work to curb spending. Less demand for goods and services reduces the pressure on businesses to keep raising prices, helping to slow inflation.
Those benefits do not come without costs. Raising rates slows economic growth, can lift unemployment and risks tipping the economy into recession if the tightening is too severe.
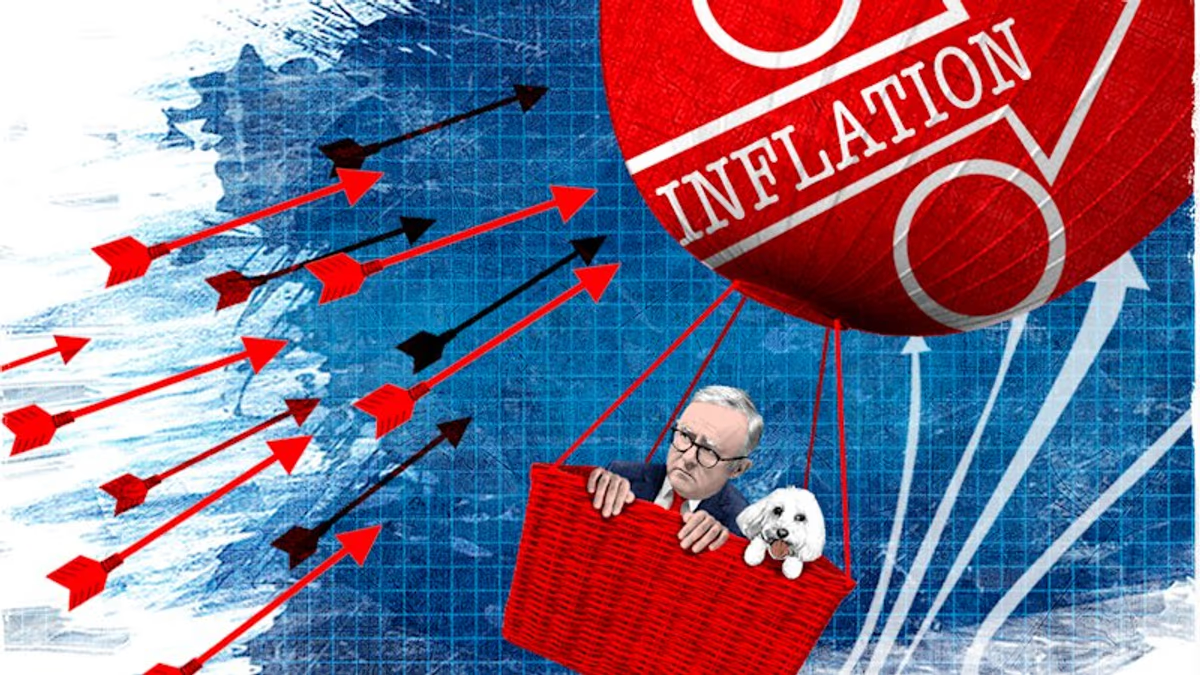
There is also a political dimension: if higher rates cause a clear downturn, responsibility and public blame often fall on the government in office, placing pressure on Prime Minister Anthony Albanese and his ministers.
For households the practical effects are immediate for many: new borrowing and existing variable loans become more expensive, while savers are likely to receive higher deposit returns. For businesses, borrowing costs rise though interest is generally tax-deductible.
Asset owners may see lower valuations for homes and shares, which can reduce perceived wealth and further restrain spending. A stronger Australian dollar can ease price pressure on imported items, directly tempering consumer prices.
With interest rates now near 4.85 per cent, the RBA’s next moves will depend on how quickly inflation slows and how economic activity responds to the higher cost of borrowing. When inflation is judged under control, the bank’s normal course is to lower the official rate again.